Financial Insights Blog |
 Working with a financial planner can be one of the most important decisions you make for your financial well-being. They help you make sense of your financial situation today and prepare for tomorrow’s goals. But how do you ensure you’re getting the most out of the process? This guide explores what financial planners do, what to consider before meeting one, how to choose the right professional, and the types of life events where planning becomes especially valuable. What Does a Financial Planner Do? At its core, a financial planner’s role is to create a roadmap for your money. This can include:
What Should I Think About Before Meeting a Financial Planner?It helps to reflect on a few areas before your first meeting:
What Should I Look at When Choosing a Financial Planner?Key factors to consider include:
 Major Life Change Considerations Financial planning often becomes most valuable during transitions such as:
The Benefits of Using a Financial PlannerWorking with a professional brings several benefits:
How to Prepare for Your First Meeting To get the most out of your first session, gather:
What Might You Ask For?During the planning process, you might ask a planner to:
Questions to Ask a Certified Financial PlannerTo make sure you’ve found the right fit, consider:
What to Consider for the Long Term Financial planning isn’t a one-time event. A strong relationship evolves as your life changes. Most people review plans annually or after big milestones. A good financial planner provides flexibility, perspective, and a process that grows with you. Getting the best out of a financial planner is about preparation, openness, and ongoing communication. By reflecting on your goals, choosing someone whose approach aligns with your values, you’ll ensure your plan continues to serve you over time.
Professionals like Tara Downs Rocchetti, CFP® provide financial planning with a focus on helping clients align money with life. Whether you’re preparing for retirement, managing a career change, or navigating family transitions, thoughtful planning can help you move forward with confidence.  Retirement planning for professionals isn’t always straightforward. Whether you're in real estate, tech, healthcare, engineering, or IT, your income patterns, tax situation, and career path all affect how you should prepare for retirement. Yet many professionals delay retirement planning until late in their careers—missing valuable opportunities for tax savings, growth, and flexibility. This guide explores how professionals from different industries can build a retirement strategy that works for their lifestyle, income, and long-term goals. Why Do Professionals Need a Tailored Retirement Plan?Many professionals face career-specific challenges:
What’s the Best Retirement Plan for Real Estate Professionals?Real estate agents typically earn commission-based income, which can fluctuate dramatically. Consider:
How Should Tech and IT Professionals Plan for Retirement?Many in tech receive compensation through stock options. A few key considerations include:
What Should Engineers Consider When Planning for Retirement?Engineers often have access to defined benefit pension plans, especially in the public sector. Those in private industry or consulting may not. Regardless:
What Are the Best Retirement Strategies for Medical and Healthcare Professionals?Doctors and healthcare practitioners often enter the workforce later due to years of education and training. Many are also incorporated. Here's what to consider:
Retirement planningSeniors for professionals is not about guessing when you’ll stop working. It’s about building flexibility and security into your future—whether you retire at 55, 65, or never fully stop. If you’re in a demanding or non-traditional profession, the right retirement strategy can make all the difference. Ready to get started? Learn more about my retirement planning and financial planning services.
Reach out today. Moving from the U.S. to Canada is exciting—but it also means big changes to your financial life. A good cross-border plan helps you avoid stress and stay on track. This guide will walk you through the most important areas to plan for: Taxes: Plan AheadBoth the U.S. and Canada may ask for taxes after you move. To avoid confusion and extra costs:
Banking and Credit: Set Up New AccountsYour U.S. bank accounts may not work the same way in Canada. Before or right after you move:
Your HomeYou may be keeping your U.S. home, selling it, or buying a new one in Canada. It’s important to think through:
Insurance: Check Your CoverageSome U.S. insurance doesn’t work in Canada. Before you move, review:
Investments: Make a New PlanIf you have savings accounts or retirement plans in the U.S., they might not work the same in Canada. Make sure to:
When Should You Start?Start planning early—at least 6 months before you move. That gives you time to:
Final ThoughtsMoving to Canada is a big step, but it doesn’t have to be stressful. With the right plan, you can feel confident that your money, taxes, and insurance are set up the right way from day one.
If you're planning a move from the U.S. to Canada, now is the time to start. Reach out to speak with Tara Downs Rocchetti today. Financial planning isn't just for people nearing retirement—it's for anyone who wants to feel more confident and in control of their financial life. Whether you're saving for a major goal, managing a recent inheritance, or simply trying to make sense of your finances, a certified financial planner can help. In this post, we explore four of the most frequently asked questions about financial planning and what you can expect from the process. What is Financial Planning?Financial planning is the process of identifying your financial goals and creating a comprehensive, personalized strategy around them. It involves evaluating your income, expenses, assets, liabilities, and current financial position, and then mapping out a plan that supports your short- and long-term objectives. A solid financial plan typically addresses a range of areas, including:
Where Does the Financial Planning Process Start?The process always begins with you. A financial planner starts by getting to know you—your values, lifestyle, financial concerns, and long-term aspirations. This discovery phase is essential, because the most effective plans are rooted in what's meaningful to you. Once your goals are clear, the next steps typically include:
Why Should I Speak to a Financial Planner?There are many reasons to speak with a financial planner, but the most common one is peace of mind. When you work with a planner, you gain a clearer picture of your financial situation and a roadmap to help you make informed decisions. Here are a few specific benefits:
What Type of Information Does a Financial Planner Require? To provide personalized and actionable advice, a financial planner needs a full picture of your financial situation. That might sound daunting, but this information is crucial to building a plan that truly works for you. Here’s what you can expect to be asked:
The goal isn’t to overwhelm you—it’s to build a strategy based on facts, not assumptions. All of the information you provide is treated with the utmost confidentiality and professionalism. A Personalized Approach to Financial PlanningNot everyone has the same goals, challenges, or starting point. Some clients are just beginning to build wealth. Others are preparing to exit a business or manage a significant inheritance. Some are focused on legacy planning, while others are simply trying to make sure they can retire when they want to. That’s why I take a personalized approach to every financial plan. My goal is simple: your financial goals are my priority. Whether you’re looking for support in one specific area or need help tying everything together, I work with you to design a plan that fits your life and evolves as you do. Ready to Start?Financial planning doesn’t have to be complicated or intimidating. It starts with a
conversation—one that’s centered on you. If you’re ready to take the next step, book a meeting with me, Tara Downs Rocchetti, CFP®. Let’s build a plan that works for you—today and into the future. 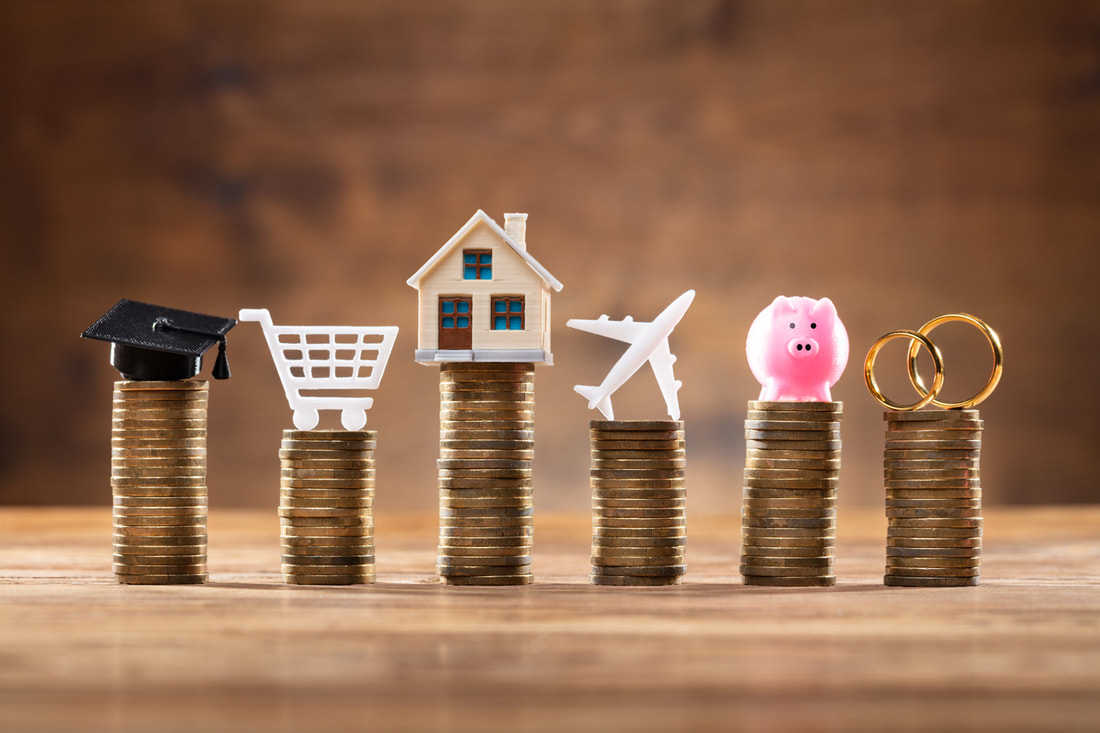 Goals are something me and other financial planners discuss frequently with our clients. Sometimes, though, it's harder for people than you might think. I get it - I used to hate the "goal setting" activities at school with a serious passion. Mainly because they were futile exercises that were never reviewed again, so I felt they were a serious waste of time.
So, how is this different? Nobody is forcing you to set arbitrary goals. You're not being graded on this. Goal setting for financial planning helps us have an idea of what is important to you and helps us create a plan so you can do more of whatever it is you love. Some people will tell me they "don't know what type of goal they're supposed to have." Guess what? There's no magic answer! Your goals are as unique as you are and your financial plans can and should be tailored to match that. I thought I might write a bit about "unique" goals I've heard clients mention (apart from the more traditional "retirement," "buying a home," "paying for my kids' education" or "making my side hustle my sole income.") Here are some of the most memorable ones (in no particular order): 1) Publishing a book. This is particularly common in academic circles where you usually need to cover all or part of the associated costs even when dealing with a reputable publisher. 2) Self-financing a "sabbatical" or "gap year" from work abroad. 3) Providing a good life for a car. Car lovers are next level. You know the type. This is similar but not to providing for a pet. For these people, this involves meticulous maintenance regiments and long relaxing drives with their mechanical loves. In these instances, I'll recognize their love for their car by including it by name in their plan. 4) Financial security for a pet. Either estate planning to ensure the pet is well cared for if you pass away or just being financially stable enough to afford a pet and all that that entails. (This is not different than providing for any other family member, in my opinion. However, many people fail to consider it so I am always so happy to hear this.) 5) Saving for fertility treatments or adoption and all those processes entail (procedures, medications, legal fees, time off work, etc.) Saving extra for baby items and mat leave is definitely a thing I discuss often. But, sometimes extra costs (emotional and financial) are involved with adding a little one to the family. 6) Saving for gender reassignment surgery. This is an emotionally, mentally and financially heavy goal. I really dislike that these and fertility procedures are considered "luxury" or "elective" procedures that often need to be financed privately to avoid massive waitlists for minimal subsidies at best. However, I'm totally here for supporting you as best I can in your efforts to live life your way. 7) Being able to afford good ______ (insert product of choice here). The heart wants what it wants. I appreciate people who are unabashedly themselves. My favourite examples of this include a person who wanted to become a politician and be able to host wine and cheese parties with quality fromage and a person who wanted to be able to afford premium "intimate adult toys" without the "guilty pleasure." What goals are you working towards? |
AuthorMy name is Tara Downs Rocchetti. I am a CERTIFIED FINANCIAL PLANNER® living in Hamilton, ON. 
Archives
February 2026
Categories
All
|
 RSS Feed
